TCF POST Report
DENVER, Oct. 28, 2026: VF Corporation (NYSE: VFC) beat its own second-quarter guidance and held its full-year outlook. Gross margin expansion and cost cuts drove operating income well above forecast, even as Vans kept shrinking.
Revenue for the quarter ended Sept. 26 fell 4% to $2.70 billion, reflecting the sale of Dickies in November 2025. Excluding Dickies, sales rose 1%, beating guidance of roughly flat. Adjusted operating income excluding Dickies reached $364 million against guidance of about $315 million, with adjusted operating margin up 170 basis points to 13.5%.
Gross margin rose 320 basis points to 55.4%. Net income climbed to $285 million from $190 million, and diluted EPS rose to $0.71 from $0.48. Adjusted EPS was $0.70, against $0.49 a year earlier on a Dickies-excluded basis.
“We drove strong results in the second quarter, ahead of guidance across key metrics, as a result of great product and solid execution,” CEO Bracken Darrell said, adding that the Vans turnaround plan is working. He claimed that the plan to reignite Vans® is working – global DTC is growing again for the first time in almost five years, "strong orders from Wholesale partners continue to give us confidence of a second-half improvement."
Performance breakdown
By brand
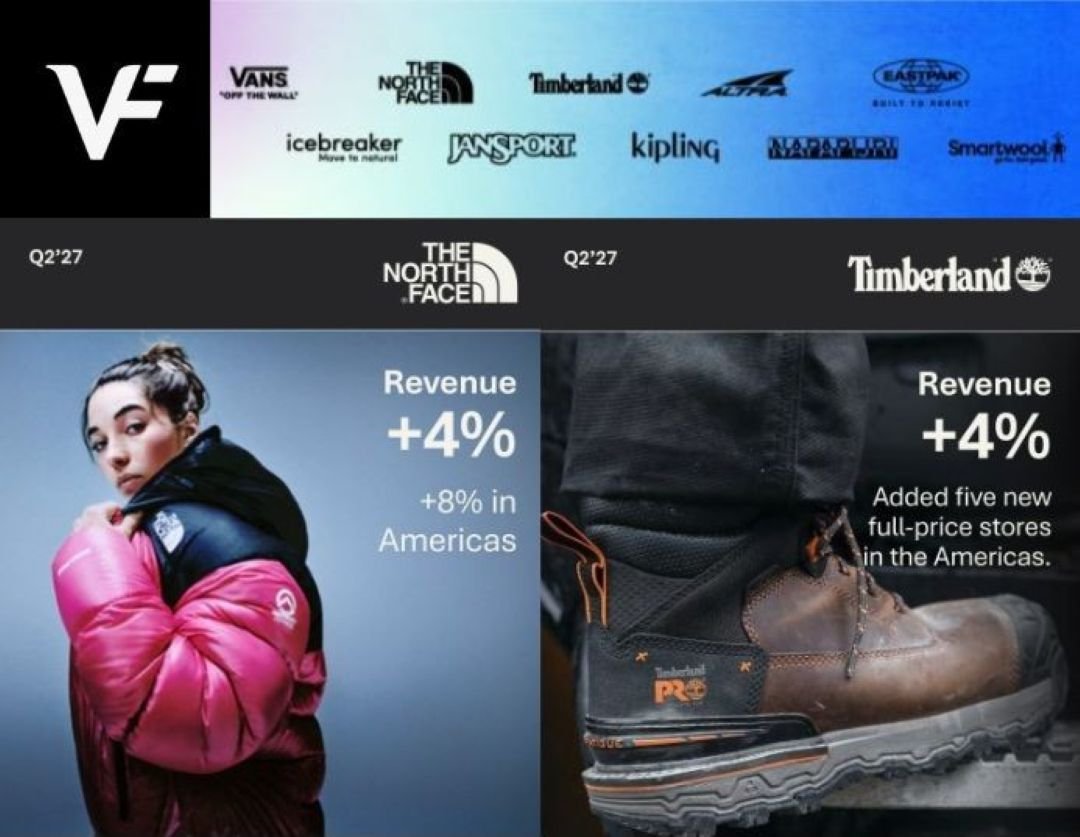
- The North Face: $1.21 billion, up 4%, with Americas up 8% and EMEA up 2%.
- Timberland: $525.9 million, up 4%, led by Americas growth of 15%.
- Vans: $547.6 million, down 10% (9.8% unrounded). Global direct-to-consumer sales grew for the first time in almost five years, but wholesale remains weak. Regional declines were Americas 6%, EMEA 15% and APAC 18%.
- Other brands: $414.3 million, down 22% reported but up 6% excluding Dickies. Altra grew more than 40%.
By channel
- Direct-to-consumer: $915.2 million, up 1% (up 3% excluding Dickies), with digital up 2% (up 8% excluding Dickies).
- Wholesale: $1.78 billion, down 6% but flat excluding Dickies. Management expects Vans wholesale to improve in the second half, citing strong orders.
- Stores: VF-operated stores totaled 1,095, down from 1,105.
- The release gives no breakdown by product category, such as footwear versus apparel.
By geography (excluding Dickies, except where noted)
- Americas: $1.32 billion, up 6% (up 5% in constant currency). Reported sales were down 2%.
- EMEA: $1.01 billion, down 2% (down 1% in constant currency). Reported sales were down 6%.
- APAC: $361.0 million, down 4% (down 7% in constant currency). Greater China fell 2%, or 7% in constant currency.
Balance sheet and outlook
Net debt fell $1.1 billion, or 20%, from a year earlier, and interest expense nearly halved to $23.7 million. Inventories rose 7% to support second-half demand. VF has not yet resumed generating cash on a half-year basis: operating cash outflow was $214 million for six months, an improvement from $372 million a year earlier.
VF reaffirmed its fiscal 2027 guidance:
- Revenue growth of 2% or better in constant dollars
- Adjusted operating margin of about 8%
- Normalized free cash flow flat to up from $405 million, with actual free cash flow of $515 million or higher
- Year-end leverage of 2.6x to 2.9x
Fiscal 2027 includes a 53rd week in the fourth quarter.
The board declared a quarterly dividend of $0.09 per share, payable Dec. 17 to shareholders of record on Dec. 10.