TCF POST 0
India Ratings and Research (Ind-Ra) has revised the outlook on the bank loan facilities of Tirupur-based Eastman Exports Global Clothing (P) Ltd (EEGCPL) to Positive from Stable. It affirmed the long-term rating at “IND A” and the short-term rating at “IND A1”. The rated facilities total INR 8,877.5 million. The agency rates the company on a consolidated basis with its wholly owned subsidiaries, Huetrap Clothing Private Limited and Eastman Exports Global Corporation (together, the Eastman Group).
Current business: earnings recover despite lower volumes
In 1HFY27, the group reported revenue of INR6,850 million and EBITDA of INR909 million. For FY26, revenue was INR13,555 million, and EBITDA was INR1,537 million (FY25: INR14,205 million and INR1,516 million). EBITDA margin rose to 13.3% in 1HFY27 from 11.3% in FY26 and 10.7% in FY25. Ind-Ra said performance exceeded its estimates. FY26 and 1HFY27 figures are provisional.
FY26 revenue fell as garment volumes dropped to 52.4 million pieces from 56.1 million, which Ind-Ra attributed to US tariffs and the West Asia conflict. Export realisations stayed stable. Margins improved on the back of FY25-FY26 capex in backward integration and plant modernisation, plus structural cuts in employee and administrative costs.
Interest coverage rose to 2.31x in 1HFY27 from 1.93x in FY26. Net adjusted leverage fell to about 2.5x from 3.4x in FY26 and 4.8x in FY25. The company has no long-term debt.
Sales are largely order-backed, with an order book of three to four months of revenue. Exports were about 88% of revenue in 1HFY27. Clients include Gap, Nautica, Ross, Decathlon, Walmart (Sam’s Club), Boardriders Group and Giordano. Recent additions include Primark, Inditex, Lacoste, J.C. Penney and DKNY.
Production capacity: full utilisation, shift in mix
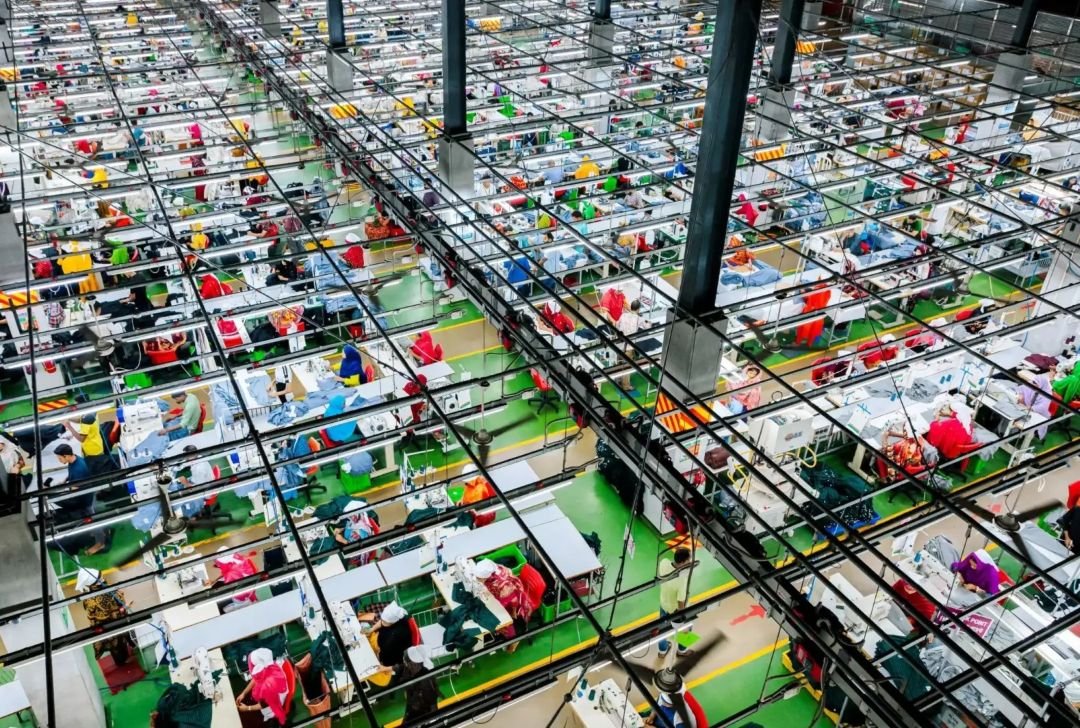
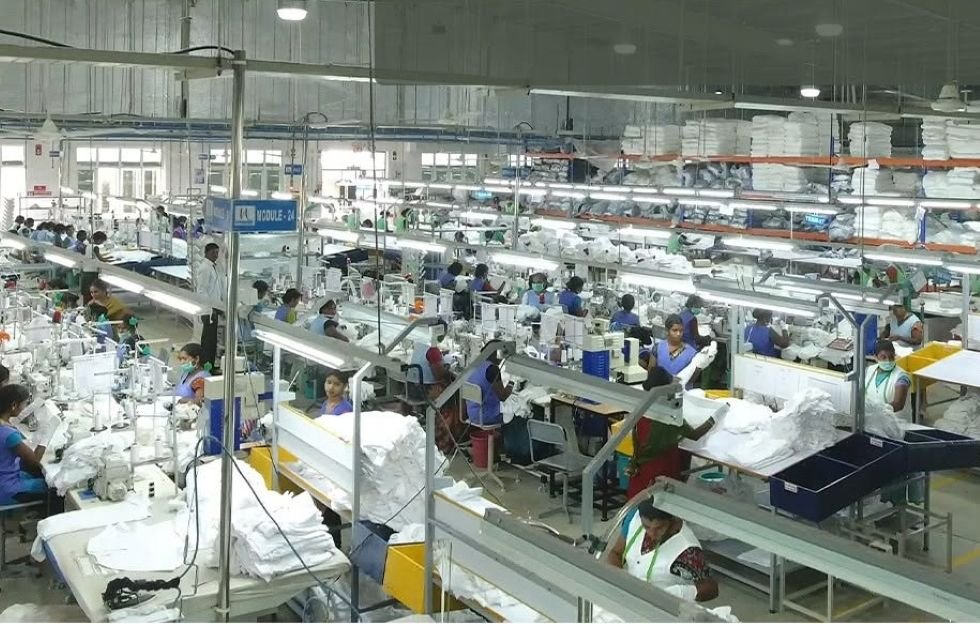
The company is operating at optimum capacity utilisation. Operations are vertically integrated across spinning, knitting, dyeing, processing and garmenting. The spinning unit, ESMPL, supplies almost half of EEGCPL’s yarn needs.
EEGCPL has filed to demerge its basics segment, about 10% of revenue. No assets are transferred, so total capacity is unchanged. The freed capacity is meant for mid- and high-fashion garments and new customers. Ind-Ra considers the demerger credit neutral. The company plans capex of INR2,000-3,000 million over FY27-FY29, to be funded mainly from internal accruals.
Liquidity
Ind-Ra rates liquidity “adequate”. Average maximum utilisation of working capital limits was about 87.7% over the 12 months to August 2026. The working capital cycle shortened to 215 days in FY26 from 219, though inventory holding remains stretched at 176 days. Free cash flow turned positive at INR842 million in FY26. Cash stood at INR4,177 million at 1HFY27-end, and no debt was taken on for working capital or capex in FY25-FY26.
Outlook
Ind-Ra expects higher EBITDA and lower leverage over FY27-FY28. It expects revenue to stay broadly stable despite the demerger, as mid- and high-fashion growth offsets the loss of basics. It also expects better global demand in FY27 and sees the UK free trade agreement and the announced EU agreement as improving Indian exporters’ competitiveness against China, Bangladesh, Vietnam and Pakistan.
A sustained rise in revenue and EBITDA that brings net adjusted leverage below 2.25x could lead to an upgrade. A substantial decline in revenue or EBITDA, a longer working capital cycle or a significant rise in debt, with leverage staying above 2.25x, could lead to a downgrade.
Risks
Concentration remains the main constraint. The top 10 customers made up about 70.1% of FY26 sales, and US customers about 62.2%. Ind-Ra also flagged limited bargaining power with large buyers, exposure to cotton prices and exchange rates, and reliance on fiscal incentives (about 6.2% of sales). The company is expanding in Europe, the UK and India to reduce its dependence on the US.